


FHA compensating factors can matter when a mortgage requires manual underwriting, but no single debt-to-income (DTI) number approves every FHA borrower. A lender must review the full loan file, including income, debts, credit, cash to close, and the property. The older version of this page presented a 56.99% DTI figure as a general approval rule. That is not a reliable way to evaluate a current application.
How do FHA DTI guidelines calculate debt-to-income ratios?
The first ratio compares the proposed monthly housing payment with effective monthly income. The second compares that housing payment plus other monthly debts with effective monthly income. The housing payment can include principal, interest, taxes, insurance, and applicable association charges. The lender determines which income and debt payments count under the current HUD Single Family Housing Policy Handbook 4000.1.
FHA’s TOTAL Mortgage Scorecard and manual underwriting are different review paths. An automated result is not a promise that a particular lender will close the loan; a file may also require a manual downgrade. Ask which path the lender is using before comparing a number from an online chart with your own application.
FHA compensating factors in manual underwriting
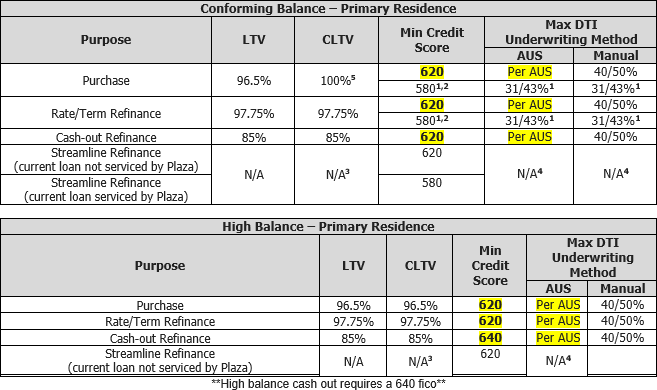
HUD’s manual-underwriting matrix expresses limits as a housing ratio followed by a total-debt ratio. For a minimum decision credit score of 580 or higher, the matrix starts at 31% / 43%. It lists 37% / 47% with one acceptable, documented compensating factor; 40% / 40% when there is no discretionary debt; and 40% / 50% with two acceptable, documented factors. A score from 500 to 579, or no credit score, generally remains at 31% / 43% under the manual matrix. The handbook has a narrow energy-efficient-home stretch-ratio provision. These are policy limits for specified manual cases, not an offer of financing or a lender’s promise to approve a file.
Acceptable factors can include verified cash reserves, a minimal increase from the current housing payment, residual income, or qualifying additional income that was not used as effective income. The type, amount, history, and required proof matter. A borrower cannot simply choose a favorable factor or count the same funds twice. Review the exact file with an FHA lender before relying on a higher ratio. HUD’s October 2026 Mortgagee Letter 2026-11 reproduces the matrix while updating credit-score methodology for FHA case numbers assigned on or after January 1, 2027; those future scoring-method changes are not current policy in October 2026.
How do credit score and down payment fit?
FHA’s minimum decision credit score is only one part of eligibility. FHA compensating factors do not override credit-score or loan-to-value requirements. The current HUD handbook limits traditional-credit transactions with scores from 500 to 579 to a maximum 90% loan-to-value ratio. Scores of 580 or higher may be eligible for maximum financing; for an eligible purchase, FHA can allow a down payment as low as 3.5%. A lender may set stricter standards, and property, income, assets, and documentation still matter. FHA mortgage insurance adds to the cost. The Consumer Financial Protection Bureau’s FHA overview explains the basic tradeoffs and recommends comparing total costs.
For a deeper explanation of the low-score tier and its limits, read our 500-credit-score FHA and VA guide. For general home-buying steps, see our purchase page.
What should I prepare for an FHA scenario review?
- Property state, approximate price or current value, and whether this is a purchase or refinance.
- Estimated credit-score range and any important credit-history context.
- Gross monthly income sources, current housing payment, and approximate monthly debt payments.
- Available funds for down payment, closing costs, and reserves, plus your target timing.
These details help a lender determine whether FHA compensating factors could apply to your scenario. To discuss them, request a mortgage conversation or call 800-917-1595. Please do not send Social Security numbers, account numbers, identity documents, or full financial statements through the general contact form. Ask for a secure document channel if a lender needs records.
Reviewed October 13, 2026. General education only; not an approval, rate quote, underwriting decision, or commitment to lend. FHA policy, lender standards, program availability, and property eligibility can change. NorthStar Funding Inc., NMLS 139369.