Specialty Mortgage Programs
Explore specialized mortgage options and learn which documentation, property, and underwriting questions may matter before you apply.

DSCR Loans for Rental Property Investors
A debt service coverage ratio (DSCR) mortgage is designed for eligible investment-property scenarios where the lender evaluates the property’s rental cash flow as part of underwriting. The complete review may also include the property, lease or market-rent evidence, credit, assets, reserves, ownership, loan pur
No Income Verification Mortgage Options
“No income verification” is a search term used for mortgage options that may use a qualifying method other than traditional pay stubs or tax-return income. It does not mean no underwriting, no documentation, or guaranteed approval. The lender may review assets, bank statements, property cash flow, credit, res
Asset Depletion and Asset Utilization Mortgage Options
Asset depletion or asset utilization is a mortgage qualifying approach that may convert eligible documented assets into a calculated income amount under a lender’s program. It is not a withdrawal plan, an investment recommendation, or automatic approval. The lender determines which assets are eligible, what red
Understanding One-Year Tax Return Mortgage Documentation
A one-year tax return mortgage review is for self-employed borrowers whose most recent federal return may better reflect their current business income than older returns. Depending on the lender and loan program, one year of returns may be considered alongside business-history, income-stability, ownership, credit
Construction-to-Permanent Mortgage Planning
A construction-to-permanent mortgage is designed with a construction phase and a longer-term mortgage phase. During the build, funds may be advanced as work progresses. The loan documents should explain what must happen before permanent financing begins. The exact structure, costs, payment schedule, and requireme

Alternative Documentation Loans for Primary and Second Homes
Alternative documentation loans may use records beyond a full set of tax returns. They can help eligible borrowers explain income from a job, business, or assets when standard records do not tell the full story. However, a lender still reviews the complete file under the rules that apply. NorthStar Funding revie

Non-Warrantable Condo Mortgage Guidance
Non-warrantable condo mortgage preparation starts with identifying the project issue behind the label. A lender may find that a condominium does not meet a particular financing standard. Ask which requirement is involved and what evidence is missing before assuming that another loan program will resolve the conce

Business Bank Statement Loans for Self-Employed Borrowers
A business bank statement loan is a mortgage option for self-employed borrowers whose tax returns may not fully reflect their current cash flow. Depending on the lender and program, a review may use eligible business deposits and the expenses needed to run the business. The lender still reviews the complete loan
FHA 203(k) Renovation Mortgage
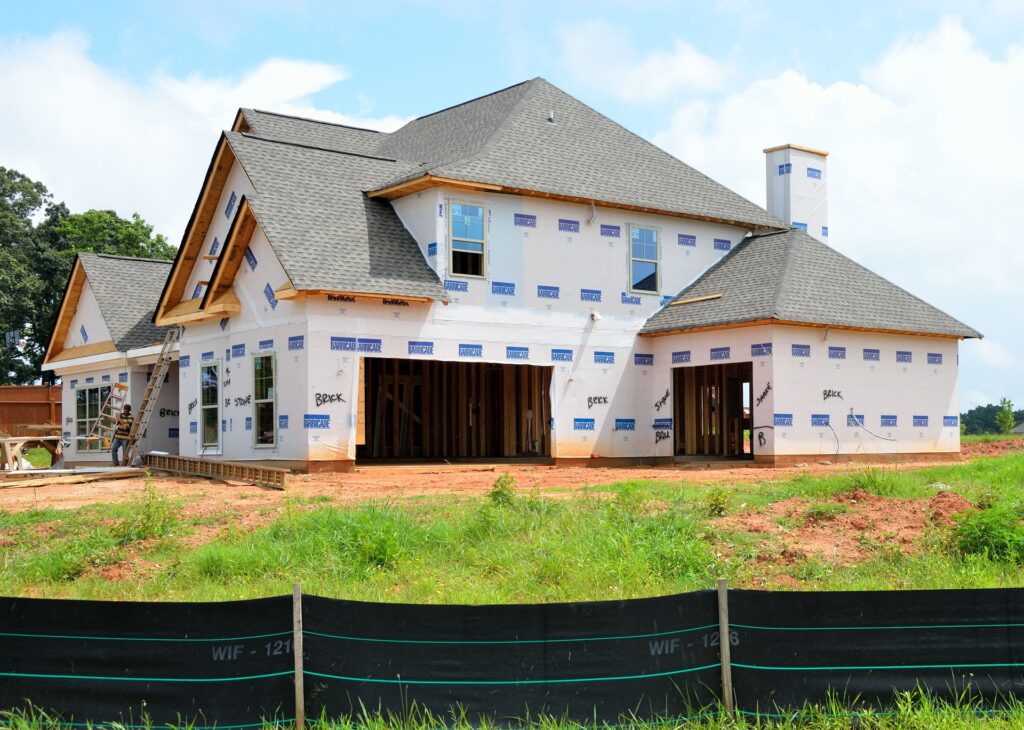
An FHA 203(k) renovation mortgage can combine a home purchase or refinance with eligible repairs or improvements. FHA insures Standard and Limited 203(k) mortgages for different project scopes. However, the property, work, borrower, and lender must meet current requirements. Plan the property and renovation to

Work Visa and Expat Mortgage Planning
Work visa mortgage planning begins with the details of your employment relocation and intended home purchase. For example, a move to the United States, an employer transfer, or a return from an overseas assignment can raise different documentation questions. In each case, your immigration or residency status, inc
Investment Coop
Investment co-op financing Investment co-op financing can require a different review from a mortgage on a condominium or a one-family home. A buyer generally acquires shares in a cooperative housing corporation and rights to occupy a particular unit under a proprietary lease. For an investment property, the co-o
Buying After Short Sale
Buying or refinancing after a short sale can require careful mortgage planning. The timing of the event, documentation, current credit profile, property, loan purpose, and applicable program requirements can all affect the options that may be available. Begin with a complete review Start with the final short-